Disability Income
A Paycheck When You Can’t Work
Disability income insurance replaces part of your paycheck if an illness or injury keeps you from working. The mortgage, the groceries and the lights don’t pause while you recover. This is the policy that keeps paying them.
Most people insure the house and the car and never insure the thing that pays for both. Your ability to earn is the biggest asset you have, and a back injury or a cancer diagnosis in your forties takes it away for months or years, not forever, but long enough to lose the house. Social Security disability exists, and it is slow, hard to qualify for and rarely enough on its own.
It happens more than people expect: the Social Security Administration estimates that about 1 in 4 of today’s 20-year-olds will face a disability before they reach retirement. You can get disability insurance on its own or add it to a life insurance policy.
How It Works
You choose a monthly benefit, usually a percentage of your income, a waiting period before benefits begin, and how long they’d pay: two years, five years, or to retirement age. If a covered illness or injury stops you from working, you wait out the elimination period and then the policy pays monthly for as long as you qualify, up to the benefit period. Every policy defines "disabled" a little differently, and that definition is the most important sentence in the contract. We’ll read it with you.
Who It Fits
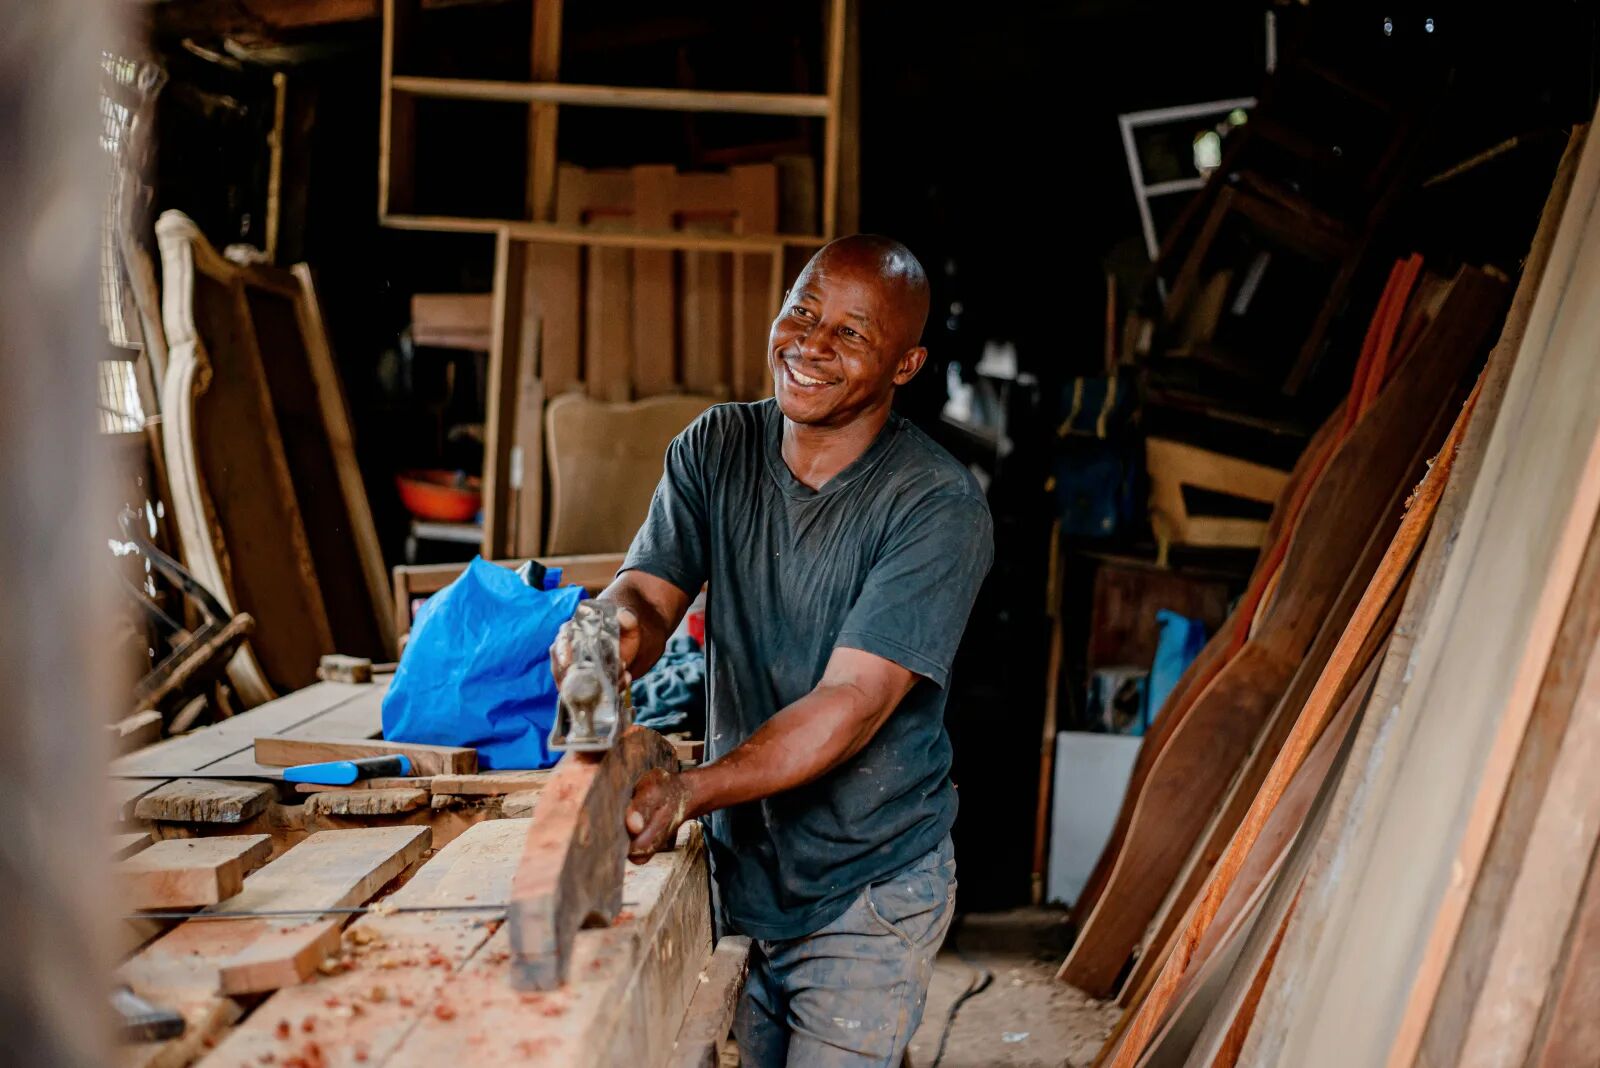
Anyone whose household depends on their paycheck and who doesn’t have a generous long-term disability plan at work. Self-employed people especially, because nobody else is going to provide it. Tradespeople and anyone whose job depends on their body.
It’s a weaker fit if you have a strong group plan through work and savings that could carry you for a year. Even then, your own policy follows you when the job doesn’t.
What the Call Looks Like
Your work, your income, what you’d need each month, how long you could manage on savings, and the health questions. Then the carriers that write disability for your occupation, side by side. Some policies are issued on the questions alone; larger benefits may call for records.
Questions People Ask
Isn’t Social Security disability enough?
It’s a backstop, not a plan. Qualifying can take many months, many first applications are denied, and the benefit is modest. Your own policy pays on its own terms.
What does "disabled" mean in a policy?
It depends on the contract. The strongest definition pays if you can’t do your own occupation; weaker ones pay only if you can’t do any job. We’ll tell you which you’re looking at.
Would I qualify?
Most people who are working and reasonably healthy do. Many carriers don’t require a medical exam, just questions about your health, your job and your lifestyle.
When should I buy it?
Sooner is cheaper. The premium is set by your age and health when you apply, and some policies can grow with your income over time.
Can I add this to a life policy instead?
Some carriers offer disability riders on a life policy that waive premiums or pay a benefit. They’re a good start and rarely a full answer. We’ll compare both.
Coverage, definitions of disability, waiting periods and prices depend on the carrier, your state and underwriting.
Why It Matters
The Paycheck Stops. The Bills Don’t.
An injury after month three. The mortgage, the car and the groceries keep coming every month. A disability policy starts paying after its waiting period, so the bills stay paid while you recover.
Request a Quick Quote
A minute of answers, then a licensed agent calls with your options, usually within one business day. No health history here; that part is a conversation.
Two Tests Every Policy Has to Pass
- It fits your budget. A premium you can carry this year and in ten.
- It meets the need. Enough coverage, of the right kind, to do the job you’re buying it for.
An option that passes only one isn’t one we’ll recommend.
A licensed agent places coverage with insurance carriers; The Comstock Agency does not underwrite or issue policies. Insurance products are offered only in the states where the agency and its agents are licensed.